
COMMERCIAL & BUSINESS LAW
Selling a Business in Queensland: How to Prepare for a Successful Sale
Selling a business is rarely as simple as finding a buyer and agreeing on a price. Preparing early can make the business easier for a purchaser to investigate, reduce delays during due diligence and help the transaction proceed more smoothly from negotiation through to settlement.
By Katie Chan
For many business owners, selling represents the culmination of years of work.
However, the legal and commercial preparation for a sale should ideally begin well before the business is advertised.
A prospective purchaser will usually want to investigate the financial performance, assets, employees, contracts, lease, intellectual property and other aspects of the business before committing to the acquisition.
Business Queensland recommends allowing as much time as possible to prepare and addressing matters such as profitability, leases, customer and supplier contracts, business assets and outstanding legal, taxation and superannuation issues before going to market.
Taking the time to prepare can help identify issues before a buyer does — when the seller still has an opportunity to address them.
1. Start Preparing Before You Find a Buyer
One of the biggest advantages a seller can have is time.
If possible, preparation should begin before the business is advertised for sale.
This provides an opportunity to:
- organise financial and corporate records;
- review key contracts;
- resolve outstanding compliance issues;
- review the commercial lease;
- identify employee entitlements;
- confirm ownership of important assets;
- address security interests;
- document arrangements that have historically been informal; and
- identify anything likely to concern a prospective purchaser.
Business Queensland specifically recommends formalising important customer and supplier relationships and addressing outstanding legal, taxation and superannuation matters when preparing for a sale.
It is generally preferable to identify a problem yourself rather than have it discovered for the first time during the buyer's due diligence.
2. Decide What You Are Actually Selling
Before marketing the business, determine exactly what is included in the proposed sale.
A business sale may involve assets such as:
- goodwill;
- plant and equipment;
- stock;
- vehicles;
- intellectual property;
- business names;
- websites and domain names;
- customer databases;
- telephone numbers;
- licences;
- customer and supplier contracts; and
- other assets used to operate the business.
Business Queensland distinguishes between tangible assets, such as equipment, and intangible assets such as goodwill, brand recognition and intellectual property when preparing a business for sale.
A seller should also identify anything that is not included.
For example, the owner may intend to retain a particular vehicle, property or other asset.
Clarifying this early makes it easier to market the business accurately and prepare the eventual sale contract.
3. Asset Sale or Share Sale?
The structure of the transaction matters.
In an asset or business sale, the purchaser generally acquires identified assets used to operate the business.
In a share sale, the purchaser acquires shares in the company that owns and operates the business.
A share sale means the company itself generally continues to own its assets, remain party to its contracts and retain its historical rights and liabilities, subject to the particular circumstances.
The two structures can have significantly different legal, taxation and commercial consequences.
Factors to consider may include:
- the nature of the assets;
- existing contracts;
- licences and approvals;
- employee arrangements;
- taxation consequences;
- existing liabilities;
- security interests; and
- the purchaser's requirements.
Your accountant and solicitor should be involved in considering the structure before the transaction is documented.
Related article: Buying or Selling a Business in Queensland: Key Legal Considerations.
4. Get Your Financial Records in Order
A serious purchaser will usually want detailed financial information.
Depending on the business, this may include:
- profit and loss statements;
- balance sheets;
- tax returns;
- BAS records;
- payroll records;
- sales reports;
- accounts receivable;
- accounts payable;
- stock records; and
- other evidence supporting the business's financial performance.
Business Queensland recommends collating financial information for prospective purchasers and notes that an independent valuation can provide a more complete assessment of a business's value.
The financial records should tell a coherent story.
If there are unusual expenses, significant fluctuations in revenue or one-off events affecting profitability, be prepared to explain them.
5. Consider Obtaining a Business Valuation
Owners understandably have strong views about what their business is worth.
A buyer may have a very different view.
Business value can be influenced by matters such as:
- profitability;
- maintainable earnings;
- assets;
- goodwill;
- customer concentration;
- recurring revenue;
- market conditions;
- intellectual property;
- lease security;
- dependence on the owner; and
- future growth prospects.
Business Queensland notes that professional valuers and business brokers can provide a more complete picture of market value, particularly because buyers and sellers commonly have different expectations.
A valuation does not guarantee the ultimate sale price, but it can provide a more informed basis for negotiations.
6. Make the Business Less Dependent on You
A business that cannot function without its owner can be harder to transfer.
Consider whether important aspects of the business exist only in the owner's head.
For example:
- are important procedures documented?
- can employees operate the business without constant owner involvement?
- are customer relationships tied personally to the owner?
- are supplier arrangements documented?
- are passwords and systems organised?
- are operational procedures recorded?
Business Queensland recommends building a capable management team and maintaining business and succession plans so that the business can continue operating through a transition.
For a purchaser, a business with established systems can present a different risk profile from one that depends almost entirely on the departing owner.
7. Review Your Commercial Lease
If the business operates from leased premises, the lease should be reviewed early.
Consider:
- how long remains on the lease;
- whether there are options;
- current rent and outgoings;
- whether the lease can be assigned;
- whether landlord consent is required;
- whether the purchaser will need to provide guarantees;
- whether there are outstanding breaches;
- whether a new lease may be preferable; and
- the process and cost of obtaining landlord approval.
The premises may be fundamental to the value of the business.
A purchaser may be unwilling to proceed if it cannot secure appropriate tenure.
Do not wait until the week before settlement to discover that landlord consent is required or that there is insufficient lease term remaining for the purchaser.
Related article: Commercial Leases in Queensland: What Business Owners Need to Know.
8. Review Your Customer and Supplier Contracts
Written contracts can add considerable value to a business — particularly where they generate recurring revenue or secure important supply arrangements.
Before going to market, review significant contracts and ask:
- are they current?
- when do they expire?
- can they be assigned?
- is the other party's consent required?
- is there a change-of-control clause?
- can the contract be terminated on short notice?
- are there outstanding breaches?
- is the arrangement actually documented?
Business Queensland recommends formal written customer and supplier contracts rather than relying solely on informal arrangements when preparing a business for sale.
A buyer is likely to place more confidence in a documented contractual relationship than an assurance that a major customer has “always stayed with us”.
9. Check Your Intellectual Property and Digital Assets
Intellectual property can represent a substantial part of the value of a modern business.
Before the sale, confirm ownership and control of assets such as:
- business names;
- trade marks;
- logos;
- copyright;
- proprietary software;
- domain names;
- websites;
- social media accounts;
- customer databases;
- marketing materials; and
- other proprietary content.
Problems can arise where material was originally created by an external contractor or former business partner and ownership was never properly documented.
Digital access should also be organised.
At settlement or during handover, a purchaser may require access to websites, domains, software, online accounts and other systems.
10. Review PPSR and Financing Arrangements
Assets used in the business may be subject to finance or registered security interests.
Before sale, identify:
- financed vehicles;
- leased equipment;
- machinery subject to security;
- business loans;
- security interests affecting assets being sold; and
- other relevant PPSR registrations.
Where a registered security interest has ended, the PPSR states that the secured party is responsible for ending or discharging the registration in a timely manner.
The sale contract may require particular security interests to be released by settlement.
Addressing these issues early can prevent them delaying completion.
11. Review Employees and Their Entitlements
Employees can be one of the most important parts of a business — and one of the areas requiring the most careful planning during a sale.
Prepare accurate information concerning:
- each employee;
- employment status;
- remuneration;
- awards or enterprise agreements;
- accrued annual leave;
- long service leave;
- personal leave;
- superannuation;
- bonuses and commissions;
- employment contracts; and
- any existing employment issues.
A sale of business may constitute a transfer of business under the Fair Work Act where the statutory criteria are met, including relevant circumstances where an employee starts with the new employer within three months, performs the same or substantially similar work and the required connection exists between the employers.
The treatment of accrued entitlements needs particular attention. A new employer must recognise prior service for many entitlements, but specific rules and exceptions apply to matters including annual leave, redundancy, long service leave, notice and unfair dismissal.
The business sale contract should clearly allocate responsibility between seller and purchaser.
12. Consider When Employees Should Be Told
Timing can be sensitive.
Telling employees too early can create uncertainty. Leaving communication too late can also cause problems.
The appropriate approach will depend on the business, transaction and applicable employment obligations.
Business Queensland recommends considering communication with employees and other important stakeholders as part of preparing for the transition.
The seller and purchaser should agree on how and when communications will occur.
13. Prepare for the Buyer's Due Diligence
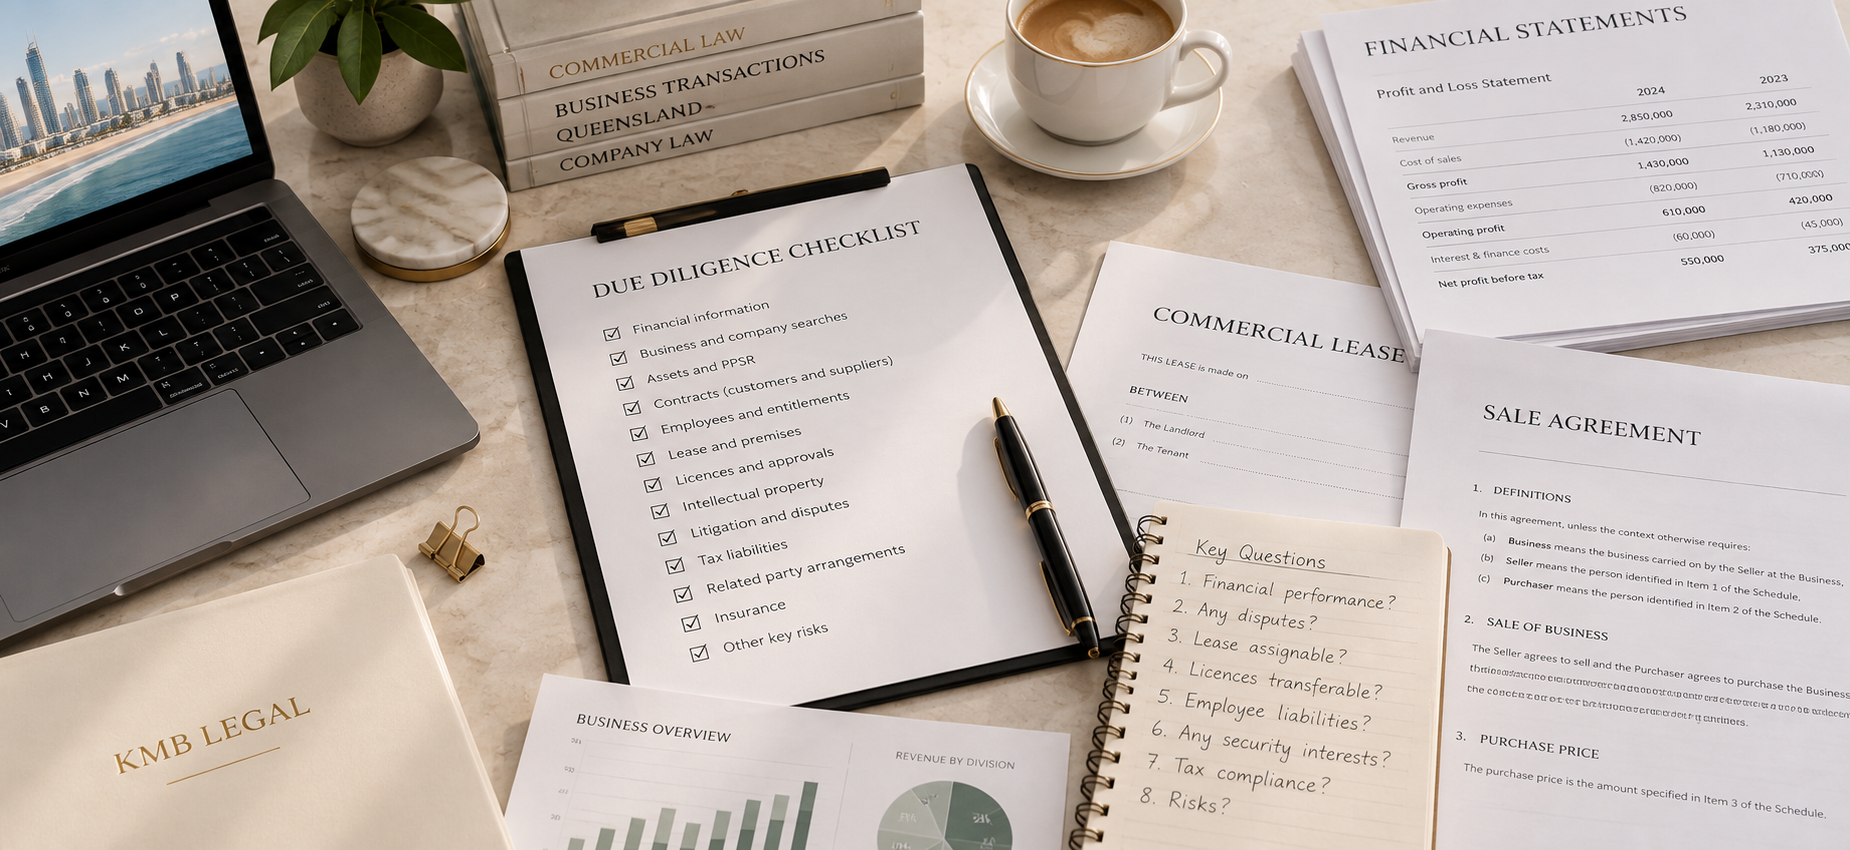
Once a serious buyer is identified, expect them to investigate the business.
They may request documents relating to:
- financial performance;
- tax;
- assets;
- employees;
- leases;
- customer and supplier contracts;
- intellectual property;
- licences and approvals;
- insurance;
- litigation;
- finance;
- corporate records; and
- compliance matters.
Business Queensland recommends reviewing due diligence material with professional advisers and being prepared to explain weaknesses or fluctuations in business performance.
Preparing an organised due diligence package can make the process more efficient and present the business professionally.
Related article: Due Diligence When Buying a Business in Queensland: What Should You Check?
14. Protect Confidential Information
A prospective purchaser may need access to highly sensitive information before deciding whether to proceed.
This might include:
- customer lists;
- pricing;
- supplier arrangements;
- financial records;
- employee information;
- intellectual property; and
- business strategies.
That information should not necessarily be handed to every person who expresses an interest in the business.
A confidentiality agreement or non-disclosure agreement (NDA) can establish obligations governing how the information is used and disclosed.
Business Queensland specifically recommends considering an NDA before providing sensitive due diligence material to prospective purchasers.
This can be especially important where the prospective purchaser is a competitor.
15. Review Your Shareholders’ Agreement
If the business is operated through a company with multiple shareholders, review the shareholders’ agreement before progressing too far with a proposed sale.
It may contain provisions dealing with:
- approval of a sale;
- transfer restrictions;
- pre-emptive rights;
- tag-along rights;
- drag-along rights;
- valuation;
- director approval; or
- other requirements affecting the transaction.
The company's constitution should also be reviewed where relevant.
Identifying these requirements at the beginning can avoid ownership issues emerging after commercial terms have already been negotiated.
Related article: Shareholders’ Agreements: Why Every Business With Multiple Owners Should Have One.
16. Heads of Agreement
Once a buyer is identified, the parties may document the principal commercial terms in a heads of agreement, term sheet or similar document.
This might record matters such as:
- purchase price;
- deposit;
- transaction structure;
- assets included;
- due diligence period;
- finance;
- lease arrangements;
- exclusivity;
- confidentiality;
- restraint terms;
- proposed settlement date; and
- other conditions.
The legal effect of such a document depends on its wording and circumstances.
Do not assume that something titled “Heads of Agreement” is automatically non-binding.
Legal advice should ideally be obtained before signing.
17. Negotiate the Business Sale Contract Carefully
The business sale contract should accurately document the commercial deal.
Depending on the transaction, it may address:
- purchase price;
- deposit;
- assets included and excluded;
- stock;
- employees;
- lease assignment;
- intellectual property;
- contracts;
- licences;
- conditions precedent;
- warranties;
- indemnities;
- restraints;
- adjustments;
- GST;
- settlement;
- training and handover; and
- post-settlement obligations.
Business Queensland emphasises that selling a business can have significant legal and financial implications and recommends professional advice during the sale process.
For the seller, it is particularly important to understand any warranties and indemnities being given.
18. Be Careful With Warranties
A purchaser may seek warranties about the business.
These might concern:
- ownership of assets;
- accuracy of information;
- financial records;
- employees;
- contracts;
- litigation;
- intellectual property;
- licences;
- taxation or compliance matters; and
- undisclosed liabilities.
A seller should not simply accept warranties because they appear in a precedent contract.
Each warranty should be considered against the actual circumstances of the business.
If exceptions need to be disclosed, they should be appropriately documented.
The sale may be completed at settlement, but liability under some contractual warranties can continue afterwards.
19. Consider the Restraint Carefully
A purchaser acquiring the goodwill of a business will commonly seek a restraint preventing the seller from immediately establishing or becoming involved in a competing business.
A proposed restraint may deal with:
- competing activities;
- geographical areas;
- time periods;
- solicitation of customers;
- solicitation of employees; and
- other activities.
The seller needs to consider the restraint in light of their plans after settlement.
For example, a person intending to retire may view a restraint very differently from someone who intends to remain active in the same industry.
The enforceability of restraint provisions depends on their terms and circumstances, so they should be carefully drafted.
20. Consider GST and Tax Before Signing
Tax advice should be obtained before the transaction is finalised.
Relevant matters may include:
- GST;
- capital gains tax;
- small business CGT concessions;
- treatment of stock;
- treatment of particular assets;
- employee liabilities; and
- whether the transaction is structured as an asset sale or share sale.
A sale of a business may potentially qualify as a GST-free supply of a going concern where the statutory requirements are satisfied.
Whether those requirements apply depends on the particular transaction.
The GST treatment should therefore be determined with the parties' accountants and reflected correctly in the sale contract rather than being left until settlement.
21. Plan for Settlement Adjustments
The purchase price is not necessarily the amount ultimately transferred at settlement.
Adjustments may be required for matters such as:
- rent;
- outgoings;
- employee entitlements;
- prepaid expenses;
- stock;
- customer deposits; and
- other amounts attributable to periods before or after settlement.
The contract should establish how relevant items are to be calculated.
The parties should also agree on how stock will be valued and whether a stocktake is required.
22. Plan the Handover
A successful business sale often involves more than transferring money and keys.
The seller may agree to assist with a transition period.
Business Queensland identifies common handover steps including introducing the purchaser to employees,
important customers and suppliers, providing training, transferring keys and security devices, providing access details for software and databases, and notifying service providers of the ownership change.
The sale contract should clearly specify:
- whether training is required;
- how long the seller must assist;
- required hours;
- whether additional assistance is paid;
- introductions to key relationships;
- transfer of systems and passwords; and
- other transition obligations.
Clear expectations reduce the risk of disagreement after settlement.
Common Issues That Can Delay a Business Sale
Some issues repeatedly create difficulties because they are discovered too late.
These include:
- lease assignment not being addressed early;
- incomplete financial records;
- unresolved PPSR registrations;
- undocumented employee arrangements;
- uncertainty about accrued employee entitlements;
- contracts that cannot be transferred;
- intellectual property owned by someone other than the seller;
- licences that cannot automatically transfer;
- disagreements between shareholders;
- outstanding taxation or compliance matters; and
- parties disagreeing about stock or settlement adjustments.
Many of these issues can be identified before the business is placed on the market.
That is why preparation matters.
Selling a Business Is a Process, Not Just a Contract
The legal contract is an important part of a business sale, but it is only one part.
A well-prepared transaction usually involves coordination between the seller's:
- solicitor;
- accountant or tax adviser;
- business broker, where applicable;
- landlord or property manager;
- financier; and
- other professional advisers.
The earlier those issues are identified and coordinated, the easier it is to structure the transaction around the seller's objectives.
Selling a Business on the Gold Coast?
KMB Legal assists business owners with selling
businesses across the Gold Coast and Queensland,
including preparing and negotiating business sale
contracts, commercial lease assignments, due diligence,
corporate documentation and settlement.
Our commercial law experience allows us to consider
both the legal documentation and the practical issues
involved in preparing a business for sale and completing
the transaction.
Free 30-minute initial telephone consultation.