
COMMERICAL & BUSINESS LAW
Buying or Selling a Business in Queensland: Key Legal Considerations
Buying or selling a business is a significant commercial transaction. Careful due diligence, a properly prepared contract and a clear understanding of the assets, liabilities and obligations being transferred can help reduce risk and avoid problems after settlement.
By Katie Chan
Whether you are purchasing your first business, expanding an existing operation or preparing to sell a business you have built over many years, the transaction involves considerably more than agreeing on a price.
A business sale may involve goodwill, equipment, intellectual property, employees, leases, licences, customer and supplier contracts, stock, security interests and taxation considerations.
The terms agreed before settlement can have significant consequences afterwards.
This article explains some of the key legal issues buyers and sellers should consider when buying or selling a business in Queensland.
Is the Transaction a Business Sale or a Share Sale?
One of the first issues is determining exactly what is being bought and sold.
In a conventional business sale, the purchaser generally acquires specified assets of the business rather than acquiring the entity that owns them.
Depending on the transaction, those assets might include:
- goodwill;
- plant and equipment;
- stock;
- intellectual property;
- business names;
- domain names and websites;
- telephone numbers;
- customer or supplier contracts;
- licences or permits; and
- the benefit of a lease.
A share sale is different. Instead of purchasing individual business assets, the buyer acquires shares in the company that operates the business.
That distinction is important because acquiring the company can also mean acquiring the company's existing history, contractual obligations and potential liabilities.
The appropriate structure should therefore be considered carefully before the transaction is documented.
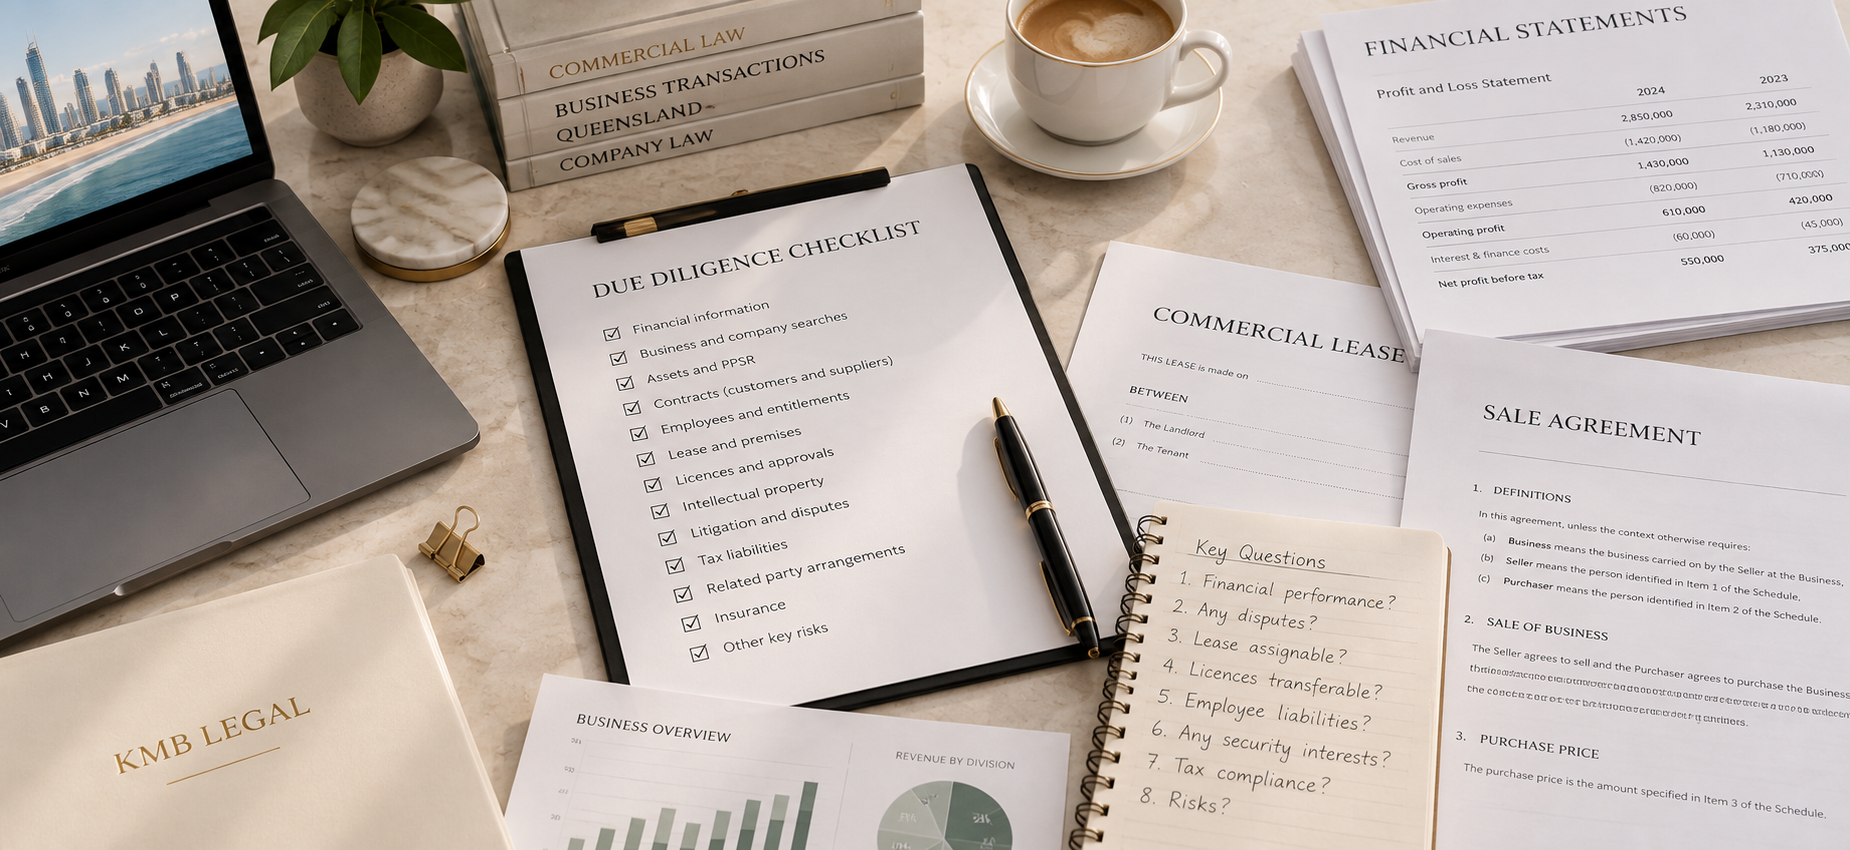
Due Diligence Before Buying a Business
A buyer should generally investigate the business before becoming unconditionally committed to the purchase.
The scope of due diligence will depend on the size and nature of the business, but may include reviewing:
- financial statements and tax records;
- business assets;
- existing contracts;
- customer and supplier arrangements;
- employees and employment obligations;
- intellectual property;
- licences and approvals;
- litigation or potential claims;
- financing arrangements;
- security interests;
- the business premises and lease;
- equipment and stock; and
- corporate records where relevant.
Due diligence is not simply about confirming the seller's financial figures. It is also an opportunity to identify legal or commercial issues that could affect the value or operation of the business after settlement.
For a buyer, discovering a significant issue before signing an unconditional contract provides considerably more options than discovering it after settlement.
Related article: Due Diligence When Buying a Business in Queensland.
The Business Sale Contract
The contract is one of the most important documents in the transaction.
It should clearly identify what is being sold and the obligations of each party.
Depending on the transaction, the contract may deal with:
- purchase price;
- deposit;
- assets included and excluded from the sale;
- stock;
- employees;
- business premises;
- intellectual property;
- licences and permits;
- contracts being transferred;
- warranties;
- restraints of trade;
- adjustments;
- conditions precedent;
- GST;
- settlement arrangements; and
- obligations before and after settlement.
A buyer or seller should ideally obtain advice before signing the contract, rather than treating legal review as something that occurs afterwards.
Once a binding contract has been entered into, the ability to renegotiate its terms may be limited.
What Exactly Is Included in the Sale?
The contract should clearly identify the assets included in the transaction.
This can be particularly important for equipment, vehicles, stock and intellectual property.
Questions may arise such as:
Who owns the equipment?
Some equipment may be leased or financed rather than owned outright.
Is the business name included?
The transaction may require appropriate steps to transfer or register business names.
Who owns the website and domain name?
The seller should ensure it actually controls the digital assets being transferred.
What about social media accounts?
Where these form part of the business's goodwill or marketing presence, arrangements for access and control should be addressed.
Is intellectual property owned by the business?
Logos, trademarks, software, designs, copyright material and other intellectual property should be identified and appropriately transferred where they form part of the transaction.
The buyer should not assume that everything used in operating the business is automatically owned by the seller or included in the sale.
The Business Premises and Lease
For many businesses, the premises are critical to the value of the business.
Where the seller leases the premises, the transaction may require the existing lease to be assigned to the buyer or a new lease to be negotiated.
Business Queensland notes that where a buyer acquires a business operated from leased premises, the seller as assignor generally requires the landlord's approval to assign the remainder of the lease to the purchaser.
The parties should consider matters such as:
- remaining lease term;
- options to renew;
- rent and rent reviews;
- outgoings;
- permitted use;
- guarantees;
- make-good obligations;
- landlord consent to assignment;
- whether a new lease is required; and
- whether the premises have the approvals required for the business.
If the premises constitute a retail shop, Queensland's Retail Shop Leases Act 1994 may also apply.
A business can be commercially successful but considerably less attractive to a purchaser if its premises cannot be secured on acceptable terms.
Employees When a Business Is Sold
Employees require careful consideration in a business sale.
A sale of business can potentially constitute a transfer of business under the Fair Work Act where the relevant requirements are satisfied.
The Fair Work Ombudsman explains that a transfer of business can occur where an employee begins working for the new employer within three months of ending employment with the previous employer, performs the same or substantially similar work, and the required connection exists between the employers.
Depending on the circumstances, the purchaser may be required to recognise an employee's previous service for certain entitlements. Different rules can apply to matters including annual leave, redundancy, long service leave, notice and unfair dismissal.
The contract should therefore clearly address issues such as:
- which employees will be offered employment;
- accrued employee entitlements;
- responsibility for those entitlements;
- adjustments at settlement;
- continuity of service; and
- any employees who will not transfer.
Employee liabilities should be investigated as part of due diligence rather than dealt with only immediately before settlement.
Contracts With Customers and Suppliers
A business may depend heavily on contracts with customers, suppliers, distributors or service providers.
A purchaser should determine whether those contracts:
- can be assigned;
- require the other party's consent;
- contain change-of-control provisions;
- can be terminated on short notice; or
- contain obligations that may affect the purchaser.
A significant customer contract may contribute substantially to the value of a business, but that value can change considerably if the contract cannot be transferred to the purchaser.
The same applies to important supplier and distribution arrangements.
Licences, Permits and Approvals
Some businesses cannot lawfully operate without particular licences, registrations, permits or government approvals.
A purchaser should establish whether the required approvals:
- transfer automatically;
- require consent;
- require a new application; or
- cannot be transferred at all.
The contract may need to make settlement conditional upon the purchaser obtaining particular approvals.
This should be investigated early, particularly where the licence or approval is fundamental to operating the business.
PPSR Searches and Security Interests
A purchaser should also consider whether assets being acquired are subject to registered security interests.
The Personal Property Securities Register (PPSR) is the national register of security interests in personal property.
Depending on the transaction, searches can assist in identifying whether another party may have a security interest affecting assets included in the sale.
This can be particularly relevant to:
- vehicles;
- equipment;
- machinery;
- inventory; and
- other business assets.
The contract may require relevant security interests to be released at or before settlement.
Warranties
Business sale contracts commonly contain warranties.
A seller may, for example, give warranties concerning matters such as:
- ownership of assets;
- accuracy of information provided;
- litigation;
- contracts;
- employees;
- compliance matters; or
- the absence of undisclosed liabilities.
From the purchaser's perspective, warranties can provide contractual protection where important representations prove incorrect.
From the seller's perspective, warranties should be reviewed carefully to ensure they are accurate and that the seller understands the potential consequences of giving them.
A seller should not give broad warranties simply because they appear in a standard-form contract.
Restraints of Trade
A purchaser is usually paying for the goodwill of the business and may therefore seek restrictions preventing the seller from immediately establishing or joining a competing business.
A restraint clause might seek to restrict competition by reference to:
- geographical area;
- period of time;
- type of business; and
- particular activities.
Whether a restraint will ultimately be enforceable depends on its terms and circumstances.
For the purchaser, an appropriately drafted restraint may be important in protecting the goodwill being acquired.
For the seller, the restraint needs to be understood carefully because it may affect future business or employment opportunities.
GST and the Sale of a Going Concern
GST should be considered before the contract is signed.
In some circumstances, a business sale can qualify as the GST-free supply of a going concern.
The ATO states that the requirements include that consideration is paid, the purchaser is registered or required to be registered for GST, the parties agree in writing that the sale is of a going concern, the seller supplies all things necessary for the continued operation of the business, and the business continues to be carried on until the day of supply.
Whether those requirements are satisfied depends on the transaction.
The GST treatment should therefore be considered with the parties' accountants and legal advisers before the contract is finalised.
Stock and Settlement Adjustments
Where stock is included in the sale, the parties need to determine how it will be valued.
The contract may provide for a stocktake shortly before or at settlement.
Other adjustments may be required for matters such as:
- rent;
- outgoings;
- prepaid expenses;
- employee entitlements;
- customer payments;
- deposits; and
- other amounts relating to periods before and after settlement.
Clear contractual provisions can reduce disagreements about settlement calculations.
Conditions Precedent
Some transactions cannot proceed until particular matters have occurred.
The contract might therefore be conditional upon matters such as:
- finance approval;
- satisfactory due diligence;
- landlord consent;
- assignment or grant of a lease;
- transfer of an important contract;
- obtaining a licence or approval; or
- obtaining necessary third-party consents.
The contract should specify what must occur, who is responsible for achieving it and what happens if the condition is not satisfied by the required date.
Confidentiality During a Business Sale
Confidentiality can be particularly important before a sale becomes public.
A prospective purchaser may require access to sensitive information about the business, including:
- financial information;
- customer lists;
- supplier arrangements;
- pricing;
- intellectual property; and
- commercial strategies.
A confidentiality agreement or non-disclosure agreement may therefore be appropriate before detailed due diligence material is provided.
For sellers, this is particularly important where the prospective purchaser is an existing or potential competitor.
Preparing a Business for Sale
A seller can often improve the efficiency of the transaction by preparing well before the business is placed on the market.
Business Queensland recommends addressing matters such as formalising important customer and supplier contracts, reviewing leases and resolving outstanding legal, taxation and superannuation matters when preparing a business for sale.
From a legal perspective, preparation might include:
- reviewing the business structure;
- ensuring key contracts are documented;
- checking ownership of intellectual property;
- reviewing the lease;
- identifying employee entitlements;
- checking licences and approvals;
- addressing security interests;
- resolving outstanding disputes where possible; and
- organising important corporate and commercial records.
A well-organised business is generally easier for a purchaser to investigate and can reduce delays during due diligence.
What Happens at Settlement?
Settlement is the point at which the transaction is completed in accordance with the contract.
Depending on the sale, settlement may involve:
- payment of the balance purchase price;
- adjustments;
- transfer of business assets;
- release of security interests;
- transfer of keys and access credentials;
- transfer of intellectual property;
- assignment of contracts;
- delivery of business records; and
- changes to control of the business.
However, settlement may not be the end of the parties' obligations.
There may also be post-settlement requirements involving employee matters, training or handover periods, transfer of licences, debtors, customer communications or other transitional arrangements.
Why Early Legal Advice Matters
Some of the most important decisions in a business transaction are made before the final contract reaches a solicitor.
The structure of the transaction, heads of agreement, due diligence conditions, lease arrangements, employee treatment, GST provisions and restraint terms can all materially affect the parties' positions.
Obtaining legal advice early can help ensure that the transaction is structured appropriately and that the contract reflects what the parties actually intend.
Buying or Selling a Business on the Gold Coast?
KMB Legal assists business owners, purchasers and investors with buying
and selling businesses in Queensland, including contract preparation and
review, due diligence, commercial leases and settlement.
Our commercial law experience allows us to consider both the legal
documentation and the broader commercial issues involved in the
transaction.
Free 30-minute initial telephone consultation.